Implied volatilities among the major asset classes declined across the board as the primary drivers of cross-asset volatility contagion, rates and oil, both eased. Interest-rate volatilities declined with the MOVE Index retreating -9pts from its 2nd highest level YTD to 98 (94th percentile high) as the 10-year yield retraced from Monday's 24-year peak of 5.35% following the strong 10-year auction with a bid-to-cover of 2.77, its highest level since 2016.
The VIX® Index declined 0.5 pts w/w to 14.8 but underperformed skew by another 0.5 pts due to opportunistic positioning for downside convexity. The marginal demand for downside protection steepened 1M S&P-500 Index 30-delta skew slightly from the 9th to 15th percentile.
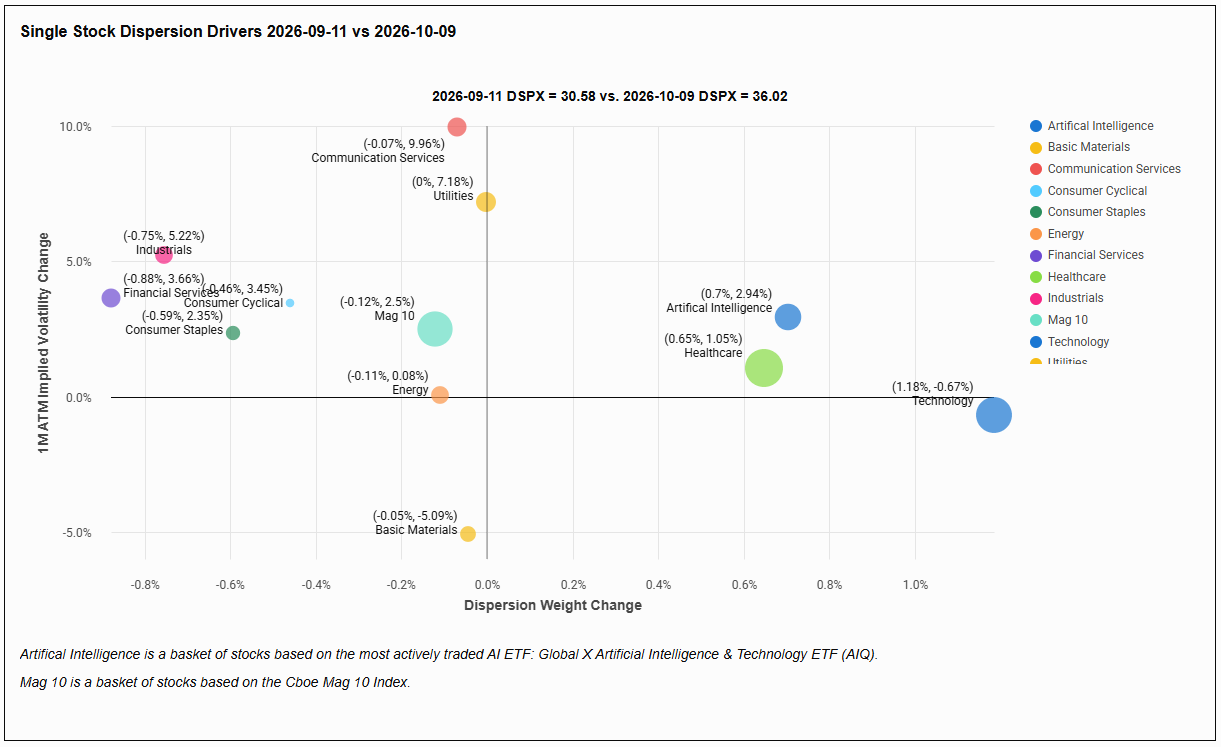
Dispersion trended higher w/w and 1M implied correlation (COR1M) declined to 6.93% (10th percentile lows) on OpenAI's revenue scare. Although the revenue gap vs expectations stemmed from an accounting definition rather than lost sales, the outsized reaction and uneven recovery among semiconductor names point to rising stock-specific risk heading into Q3 earnings.
Chart: Stock Dispersion Increasing into Earnings Season as Traders Differentiating Both, Within Tech and Across the Broader Market