Implied volatilities were mixed across major asset classes last week as hotter-than-expected September CPI and PPI reports revived Fed rate-hike fears and collided with mounting worries about debt-funded AI spending. Despite hotter-than-expected readings in core CPI and headline PPI, interest-rate volatility held steady. The MOVE Index hovered in a tight 99–102 range (92nd–94th percentile) all week, a sign the rates market had already priced in this scenario. The 10-year Treasury yield briefly jumped to 5.33% after the CPI release, then reversed on safe-haven demand to finish the week down 15 bp at 5.10%.
Credit volatility rose last week (VIXHY & VIXIG climbed in tandem from 75th to 86th percentile highs) as investors repriced the debt-funded AI buildout not only for CoreWeave and other high-yield AI firms, but also for investment-grade borrowers such as Oracle and the capex-intensive hyperscalers.
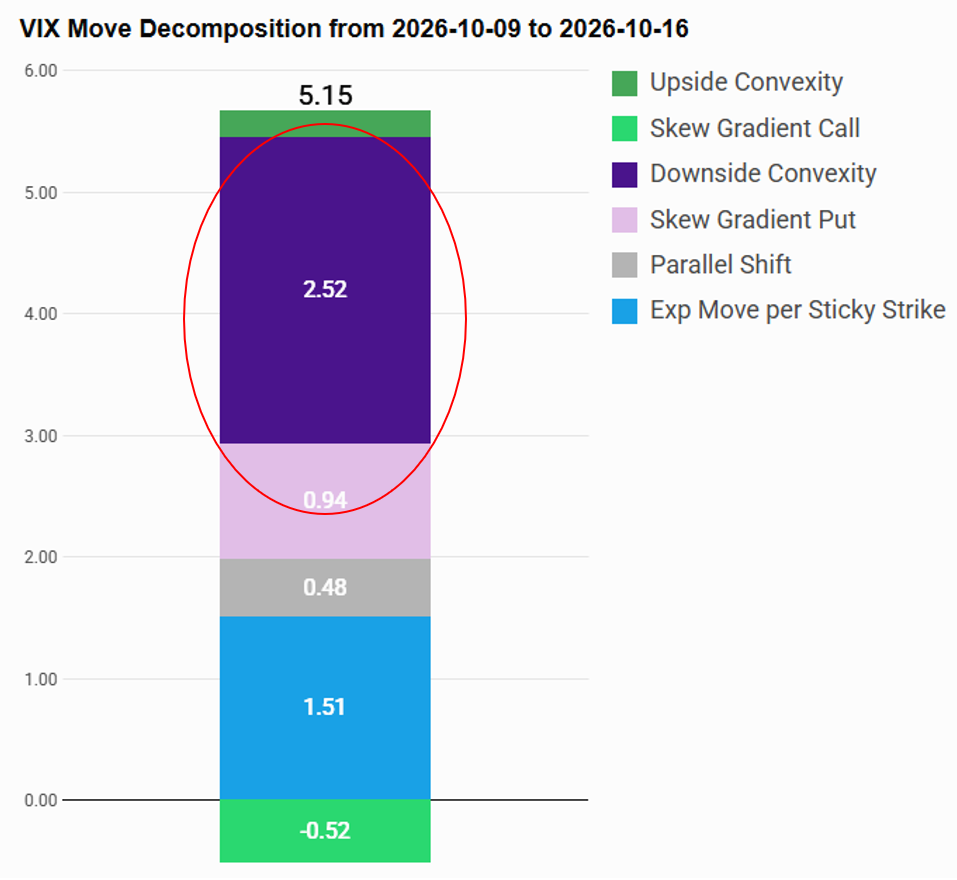
The VIX® Index rose 5 pts w/w to 20, outpacing the move implied by skew by 3.5 pts; driven primarily by demand for downside convexity. The strong demand for downside protection steepened 1M S&P-500 Index 30-delta skew from 15th percentile lows to 82nd percentile highs. The overall demand for optionality accelerated into the weekend: Friday’s SPX and XSP options volume was the 4th- and 5th-highest on record.
Starting today, traders will get an extra 130 minutes per day to trade options on 29 large-cap stocks and ETFs, including SPY, QQQ, IWM, NVDA, TSLA, AAPL,INTC, MU,META, AMZN, AMD, MSFT, GOOGL, and more. For full list, see here. This new session runs from 730AM ET until 925AM, with trading extended an additional 15 minutes at the end of the day for the non-ETF symbols.
Chart: VIX Higher w/w on Demand for Tail Convexity & Core Hedges