Risk assets sold off last week as oil prices jumped to a 3-month high on escalating Middle East tensions and US core inflation surprised to the upside. Oil volatility jumped the most across asset classes, with the OVX Index up 14 pts wk/wk to 59%. Higher oil prices are adding fuel to the sticky inflation worries in the US, with the odds of a Fed rate hike at this week’s FOMC meeting rising from 58% to 90% in the OIS market. SPX® weekly options are pricing in ~1.1% implied move for Wednesday’s Fed announcement.
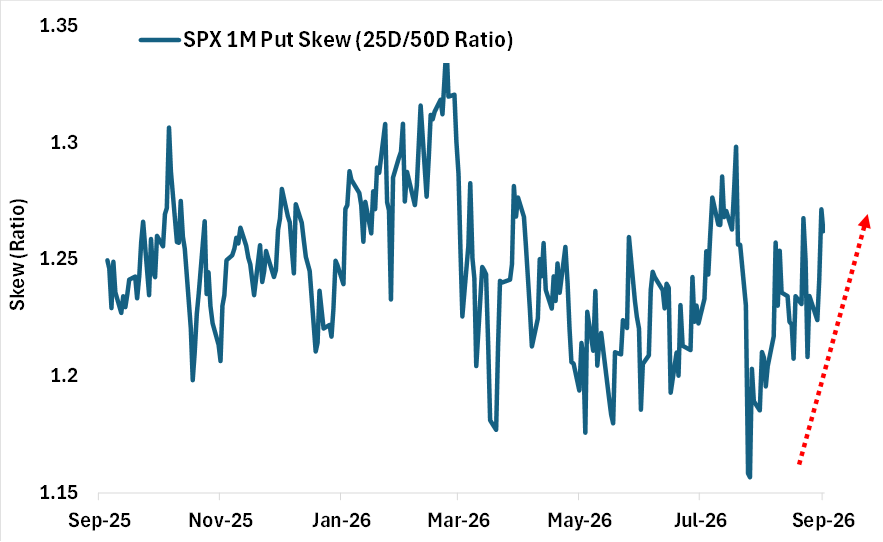
The VIX® Index gained 1.3 pts last week to 15.8%, with more than half of the move coming from a steepening in SPX skew and convexity. SPX 1M put skew (25-delta/50-delta ratio) jumped to the 73rd percentile high on the back of increased hedging demand. Single stock volatility diverged notably from index vol, as the VIXEQSM Index fell 1.3 pts to 34.5%. The VIXEQ-VIX Index spread has now halved from its record high of 34% in July as risk in the equity market has shifted from the micro (earnings & AI) to macro (inflation & rates). As fears over the AI trade have subsided, so has the volatility premium in Tech stocks, with the QQQ-SPX 1M implied volatility spread now trading near a 1-year low of 3.6%.
Tail hedging in the equity market has picked up as well, particularly via VIX options. Three of the four largest VIX trades year-to-date have occurred in the past two weeks, with a customer buying over 120k contracts of outright VIX calls in each instance (each trade ~$12M in premium, with strikes ranging from 28-34 in the Oct and Nov expiries).
Chart: SPX Put Skew Steepens on Increased Hedging Demand